Professional Indemnity Insurance
Protect your professional reputation and finances when a client alleges that an error, omission, negligence, or other professional failure in your work has caused them financial loss. Professional Indemnity Insurance is designed for professionals and service businesses whose expertise, advice, or work creates a potential liability to their clients.
What is Professional Indemnity Insurance?
Imagine you're a consultant and your advice leads to a client losing a significant amount of money. The client holds you responsible and decides to take legal action.
Professional Indemnity Insurance (PII) helps protect you against claims arising from your professional services, covering legal defence costs and compensation where covered by your policy.
Professional Indemnity Insurance
Professional Errors and Omissions
Protection against covered claims alleging that an error, omission or negligent act in your professional service caused a client financial loss.
Legal Defence Costs
Cover for eligible legal and defence expenses arising from a covered claim, subject to the policy terms and applicable limits.
Professional Negligence
Protection against covered claims alleging that your professional advice, service or work fell below the required professional standard and caused the client a financial loss.
Breach of Professional Duty
Protection against certain covered claims arising from an alleged failure to meet a professional duty owed to a client.
Compensation and Damages
Where covered and legally payable, the policy may respond to compensation or damages awarded against the insured as a result of an insured professional liability claim.
Libel and Slander
Some Professional Indemnity policies may provide cover for certain claims involving alleged libel or slander arising from professional activities, subject to the specific policy wording.
Important: Professional Indemnity Insurance does not cover every dispute with a client. The claim must fall within the insured professional activities and the policy's terms, conditions, exclusions and applicable limit of indemnity.
Deliberate or dishonest acts
Fraudulent, dishonest or intentionally wrongful conduct is generally excluded.
Known circumstances
Claims or circumstances that were known or should reasonably have been known before the policy began may not be covered.
Contractual liabilities
Certain liabilities accepted solely through a contract may be excluded or restricted beyond liabilities that would otherwise exist at law.
Bodily injury or property damage
These may fall under Public Liability or other forms of insurance rather than Professional Indemnity, depending on the circumstances.
Fines and penalties
Criminal fines, statutory penalties and certain punitive amounts are generally not insurable.
Uninsured professional activities
Work or services outside the professional activities declared and accepted by the insurer may not be covered.
Important: The exact exclusions vary by insurer and profession. We'll help you understand the scope of cover before arranging the policy.
Is this cover right for you?
It is particularly relevant if you are:
- An accountant, auditor, consultant, financial adviser or management professional
- An architect, engineer, surveyor, quantity surveyor or other technical professional
- A lawyer, technology professional, IT consultant, software provider or other specialist service provider
- A professional services firm whose clients could suffer financial loss because of an error or omission in the services you provide
Ready to protect your professional practice?
Tell us about your profession, the services you provide, the clients you serve, and the level of exposure involved. We'll help you identify the appropriate Professional Indemnity cover for your practice or business.
Get a Custom QuoteFAQs
For some regulated professions, professional indemnity requirements may apply through legislation, professional bodies, regulators or contractual arrangements. The requirement depends on the profession and circumstances. We can help you establish what level of cover may be appropriate.
It can, where the employees' activities fall within the professional services insured under the policy and the claim otherwise satisfies the policy terms and conditions.
Potentially, yes. Professional liability claims can sometimes arise after the professional service has been completed. Whether a particular claim is covered depends on the policy period, retroactive date, notification requirements and other terms.
Not every breach of contract is covered. The policy is primarily designed for professional liability arising from insured professional services, and contractual liabilities may be excluded or restricted. The specific circumstances and policy wording matter.
The appropriate limit depends on factors such as your profession, annual turnover, client contracts, size and value of projects, potential severity of a claim and any regulatory or contractual requirements. We can help assess the level of exposure before obtaining quotations.
You may also be interested in
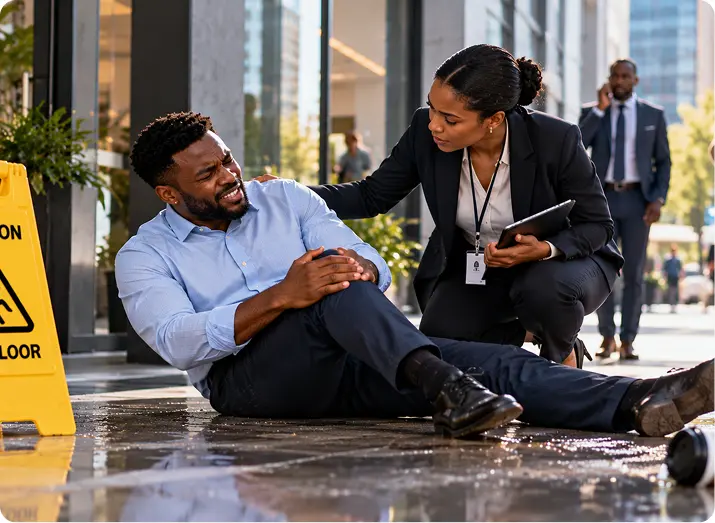
Public Liability Insurance
Protection against covered third-party claims arising from accidental bodily injury or property damage connected with your business activities.
Employers' Liability Insurance
Protection against certain liabilities arising from injury or illness suffered by employees in connection with their employment, where applicable.
Cyber Insurance
Protection against specified financial and liability risks arising from cyber incidents, data breaches and other covered cyber events.