Public Liability Insurance
Protect your business if a customer, visitor, or member of the public is injured or their property is accidentally damaged because of your business activities. Public Liability Insurance helps cover eligible compensation and legal costs when your business is held responsible.
What is Public Liability Insurance?
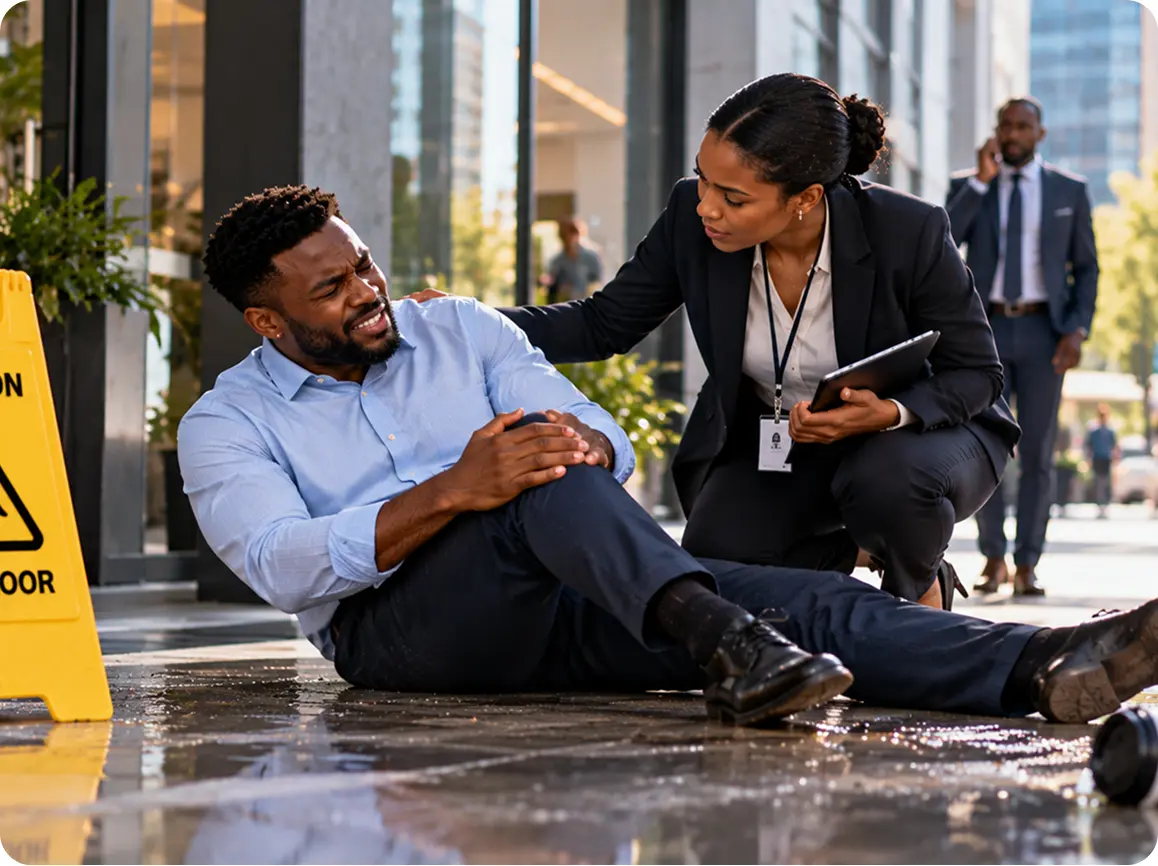
Public Liability Insurance provides protection against your legal liability for certain third-party bodily injury or property damage arising from your business activities.
For example, a customer could be injured at your premises, or your business could accidentally damage someone else's property.
Where a covered claim is established, the policy can help with eligible compensation and associated legal costs, subject to its terms and limits.
Public Liability Insurance
Third-Party Bodily Injury
Protection against covered claims arising from accidental bodily injury suffered by a member of the public in connection with your business activities.
Third-Party Property Damage
Protection against covered claims for accidental damage to property belonging to another person or organisation caused by your business activities.
Legal Defence Costs
Cover for eligible legal expenses incurred in defending a covered liability claim, subject to the policy terms and applicable limits.
Incidents at Your Premises
Protection against covered liability arising from accidents involving customers, visitors or other third parties at your business premises.
Incidents During Business Operations
Protection against covered third-party liability arising from your business activities away from your premises, where those activities fall within the scope of the policy.
Products Liability
Where specifically included, protection against certain third-party claims for bodily injury or property damage caused by products supplied by your business.
Important: Public Liability Insurance responds to covered legal liabilities. It does not mean that every accident, injury, complaint or demand against your business will automatically result in an insurance payment.
Professional errors or advice
Claims arising from professional negligence, errors or omissions may require Professional Indemnity Insurance instead.
Employee injuries
Injuries to employees arising from their employment are generally dealt with under employers' liability, workers' compensation or other applicable arrangements rather than Public Liability.
Intentional acts
Deliberately caused injury or damage is generally excluded.
Contractual liabilities
Certain liabilities accepted solely through a contract may be excluded or restricted.
Damage to your own property
Damage to property owned by your business is generally not the purpose of Public Liability cover.
Motor-related liabilities
Liability arising from the ownership or use of motor vehicles may require Motor Insurance or another specific policy.
Important: The exact exclusions depend on the policy wording, your declared business activities and the cover arranged.
Is this cover right for you?
It is particularly relevant if:
- You operate a shop, office, restaurant, hotel, school, clinic, warehouse or other premises visited by customers or members of the public
- Your business installs, repairs, delivers, builds or provides services at customers' premises
- You regularly have customers, contractors, suppliers or visitors interacting with your business
- Your contracts, landlords, clients or project requirements require evidence of Public Liability Insurance
Ready to protect your business against third-party liability?
Tell us about your business activities, premises, customers, and the types of risks you face. We'll help you identify the appropriate liability protection for your business.
Get a Custom QuoteFAQs
It can, where the business is legally liable, and the circumstances fall within the policy's coverage. The specific cause of the injury, circumstances of the incident, and policy terms will determine whether a claim is covered.
Potentially, yes. Accidental damage to third-party property arising from your insured business activities can be covered, subject to the policy terms, exclusions and limit of indemnity.
It is not primarily designed to cover employees for injuries arising from their employment. Separate employers' liability or workers' compensation arrangements may apply depending on the circumstances and applicable requirements.
No. Public Liability primarily addresses third-party bodily injury and property damage arising from business activities. Professional Indemnity is designed for certain claims arising from professional errors, omissions, negligence, or failures in professional services.
Yes. A client, landlord, contractor or project owner may require evidence of liability insurance as part of a contract or site-access requirement. The required limit and scope of cover can vary depending on the contract and activity.
You may also be interested in
Professional Indemnity Insurance
Protection against certain claims arising from professional errors, omissions, negligence or failures in professional services.
Employers' Liability Insurance
Protection against certain liabilities arising from employee injury or illness connected with their employment, where applicable.
Fire, Burglary and Special Perils Insurance
Protection for your premises, stock, equipment and other insured property against specified property risks.